A construction loan works differently from a standard home loan. Instead of handing over the full amount at settlement, the lender releases the money in stages as your build progresses, and you only pay interest on what’s been drawn. That structure protects both you and the lender, but it also means the loan has more moving parts: a fixed-price building contract, staged valuations, and a builder the lender is willing to back.

At Loanworx, we arrange construction loans for people building a new home, replacing an existing one, or buying land and building on it. We compare lenders across the market, match you to one comfortable with your contract and builder, and manage the progress payments so each stage of the build is funded on time. Whether it’s a single dwelling, a knockdown rebuild or a house-and-land package, we keep the finance moving in step with the construction.

As an experienced finance broker, we work for you rather than for any single lender. That means structuring the loan correctly from the start, explaining the drawdown process in plain language, and coordinating with your builder and the lender so a delayed payment never holds up the trades on site.

Planning a build, a rebuild or a land-and-construction purchase? Call us on 1300 562 696 or get in touch and we’ll be back to you shortly.

Finance Matched to Your Build

No two builds are identical. The right loan depends on whether you already own the land, whether you’re rebuilding on an existing block, and which builder and contract you’re using. Each of those changes the lender’s appetite and the way the loan is structured.

We assess your build, match it to a lender comfortable with that scenario, and set the loan up so the land settlement and the construction drawdowns flow without gaps. The aim is a clean run from the first progress payment to the final inspection, with the finance never the thing that stalls the job.

How We Help with Construction Loans

We support a wide range of construction scenarios, including:

  • Knockdown rebuilds
    Using existing equity and a construction loan to replace an older home with a new build.
  • Major renovations and extensions
    Funding structural changes, second-storey additions, and significant upgrades.
  • New home builds on vacant land
    Buying land and building later, or arranging land + build at the same time.
  • Dual occupancies and townhouses
    Small development or investment projects where multiple dwellings are built on one block.
  • Owner-builder projects
    Helping you understand which lenders will consider your build and what extra documentation they require.

We’ll review your building contract, plans, and costings, then recommend a construction financing strategy that fits your budget and risk profile.

Why Plan Your Construction Finance Early?

How a Construction Loan Works

A construction loan is built around the way a home is actually built: in stages, each one inspected and valued before the next is funded. Here are the three features that set it apart from a standard home loan.

Progressive drawdowns by stage

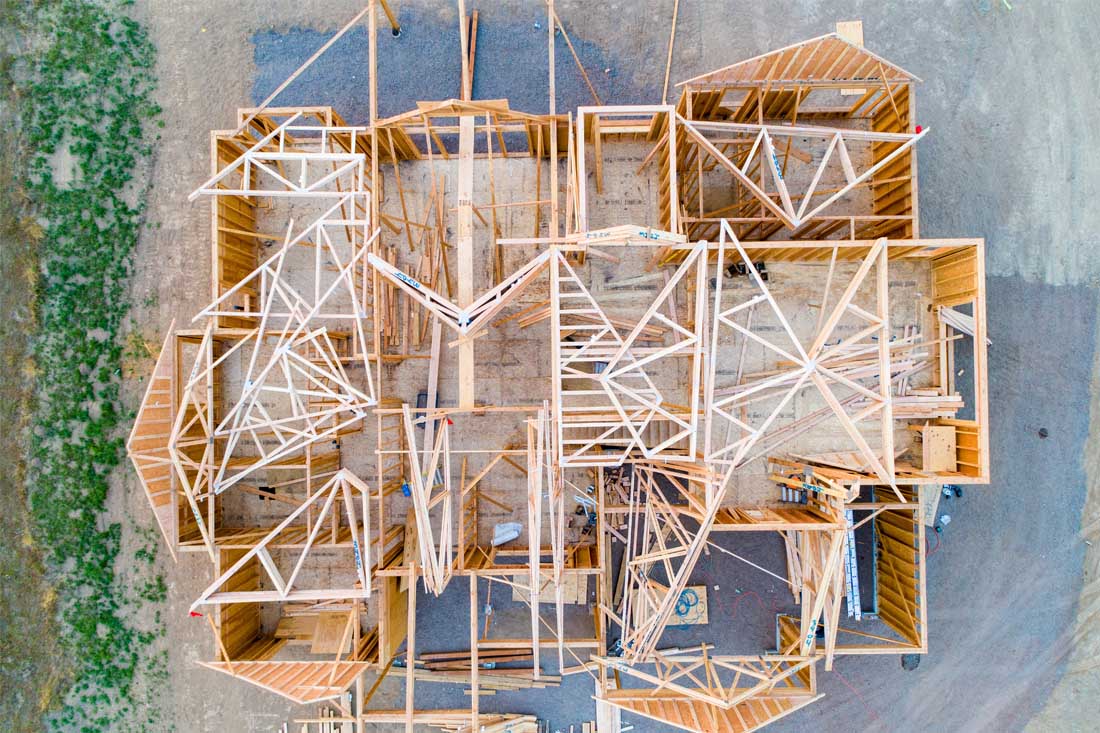
Rather than one lump sum, the loan is released in progress payments that line up with the build. The typical stages are deposit, slab or base, frame, lockup, fixing or fit-out, and completion. The lender pays your builder at each milestone, usually after a valuation confirms the work is done, so the money matches the progress on site.

Interest only on what’s drawn

During construction you pay interest only on the amount actually released, not the full loan. Early in the build, when only the deposit and slab are drawn, repayments are low; they rise as more is released. This keeps holding costs manageable while you may also be paying rent or an existing mortgage.

A fixed-price building contract

Most lenders want a fixed-price building contract with a licensed builder before they’ll approve the loan. It tells the lender exactly what’s being built and for how much, which underpins the on-completion valuation. Cost-plus and owner-builder arrangements are possible but sit with a narrower lender panel and tighter terms.

Contact Us Now

What Lenders Look At for a Construction Loan

Construction lending carries a few extra checks a standard purchase doesn’t, because the security is a home that doesn’t exist yet. These are the factors lenders weigh before approving a build:

01. The building contract and plans

Lenders assess the fixed-price contract, the plans and the council approvals to understand exactly what’s being built and for how much. A clear, fixed-price contract with a licensed builder is the strongest position. Cost-plus contracts and changes mid-build are workable, but they narrow the lender panel and can affect the valuation, so we flag them early.

02. The on-completion valuation

Because the home isn’t built yet, the lender orders a valuation based on the land plus the contract, giving an “as if complete” value. The loan-to-value ratio is calculated against that figure. If the on-completion value comes in below the combined land and build cost, the lender may lend less than expected, which is something we plan for upfront.

03. Your deposit and land equity

If you already own the land, its equity often counts toward your contribution, which can reduce or remove the cash deposit needed for the build. For a land-and-construction purchase, the deposit covers both components. We work out how your land equity and cash combine so you know exactly what’s needed before you sign the building contract.

04. Serviceability through the build

Lenders check you can service the loan at completion on a principal-and-interest basis, while also coping with the interest-only repayments during construction, which may overlap with rent or an existing mortgage. Matching you to a lender comfortable with that overlap is often what turns an approvable build into a smooth process.

05. The builder and the build type

The builder matters as much as the borrower. Lenders look for a licensed, accredited builder with appropriate insurance and home warranty cover, and they treat standard single dwellings more comfortably than owner-builder projects, knockdown rebuilds or unusual designs. Owner-builder loans are possible but generally come with lower loan-to-value ratios and a much narrower lender panel. We flag where your builder or build type may limit the options before you commit.

Explore Our Other Home Loan Services

Building a home often overlaps with other needs, from buying the next place to refinancing once the keys are in hand. Our other home loan services cover the rest of the journey. Explore the options below to find the right fit for your plans.

Finance for your next move, with the buying and selling coordinated around you.

Borrow inside your self-managed super fund to buy property under a limited recourse borrowing arrangement.

Secure a property before completion, with finance timed to a settlement that may be months or years away.

Finance for your next move, with the buying and selling coordinated around you.

Loans structured around an investment property, your rental income and your wider tax position.

Switch to a sharper rate, unlock equity, consolidate debt or restructure your existing loan.

Why Borrowers Choose Loanworx

A construction loan isn’t only about the headline rate. It’s about being matched to a lender comfortable with your build, structuring the drawdowns so the job never stalls, and having someone manage the process end to end.

  • Whole-of-market comparison: We compare construction loans across a broad panel of banks, second-tier lenders and non-bank funders, so you see a genuine spread of options rather than one lender’s offering.

  • Senior brokers who structure the deal: You deal with experienced brokers who shape the application before it’s lodged. We expect to see fixed-price contracts, land equity, staged valuations and owner-builder scenarios, and we know how to present each one to the lender accurately.

  • Drawdowns managed through the build: Construction loans live or die on the progress payments. We coordinate the drawdowns with your builder and the lender at each stage, so the trades get paid on time and the job keeps moving rather than waiting on paperwork.

  • Clear fee and commission disclosure: For most construction loans, Loanworx is paid an upfront and trail commission by the lender after settlement, and that commission typically does not change the rate or fees you pay. Where a fee for service applies to a more complex scenario, we disclose it in writing before any work begins.

Why Plan Your Construction Finance Early?

Construction loans involve more checks and documentation than standard home loans. Planning early can help you understand what’s required, structure your finance correctly, and avoid delays once your build is ready to move forward.

Pre-approval timeframes vary depending on the lender and project complexity, but many clients receive an outcome within a few weeks once all required information is provided.

Discover a smarter way to fund your build.

Contact Us Now

Things You Should Know About Construction Home Loans

Construction home loans can offer more control and flexibility during your build, but they’re not the same as a standard mortgage. It’s important to understand both the benefits and the potential challenges.

Potential Benefits:

  • Interest is usually charged only on the funds drawn at each stage
  • Staged drawdowns can help manage cash flow as work progresses
  • Loan structures tailored to owner-occupiers, investors, and developers
  • Ability to use existing equity to help fund a knockdown rebuild or new build
  • Options for funding single homes, duplexes, townhouses, and small multi-unit projects
  • Support from a construction finance specialist who understands lender policy

Things to Watch:

  • Lenders require detailed contracts, plans, and cost breakdowns
  • Budget changes mid-project can trigger reassessment or extra conditions
  • Some lenders are restrictive with owner-builder loans
  • Interest-only construction periods often roll to principal & interest at completion
  • Cost variations or delays can impact valuations and approval conditions
  • There is more paperwork and more steps than with a standard home loan

We’ll help you anticipate these issues and prepare the documentation your lender is likely to need.

Banks and Lenders We Work With

Loanworx works with a wide panel of Australian banks and specialist construction lenders. This gives you access to both mainstream and more flexible options, rather than being limited to a single bank’s policy.

We use our experience and lender relationships to find a construction financing solution that suits your project size, location, and timeframes.

Our Construction Financing Process

Getting construction finance doesn’t have to be complicated. Our four-step process is designed to keep your project moving smoothly.

Step 1: Book a Free Consultation

We review your building plans, financial position, and project goals.

Step 2: Compare the Right Options

We compare a range of construction loans and outline the pros and cons of each structure for your situation.

Step 3: Get Pre-Approval

 We help you secure pre-approval so you and your builder can plan with confidence.

Step 4: Buy & Settle

 We manage the settlement process and work with your lender during the construction phase to ensure progress payments are released on time.

Speak to a Construction Finance Specialist

Frequently Asked Questions

How does a construction loan release the money?

The loan is paid out in stages, called progress payments or drawdowns, that match the build. The usual stages are deposit, slab or base, frame, lockup, fixing or fit-out, and completion. As each stage finishes, the lender (often after a brief valuation) releases that portion of the loan directly to your builder. You don’t receive the full amount upfront, and you only pay interest on what’s been drawn so far.

Do I pay interest on the whole loan during construction?

No. During the build you pay interest only on the amount that’s actually been drawn down, not the full approved loan. Early on, when only the deposit and slab have been released, repayments are low; they increase as more of the loan is drawn at each stage. Once the home is complete, the loan typically converts to a standard principal-and-interest home loan on the full balance.

What deposit do I need for a construction loan?

It works much like a standard home loan, measured against the on-completion value of the property (land plus build). A contribution that keeps you at or below 80% of that value avoids lenders mortgage insurance (LMI), and smaller deposits are workable with LMI added. If you already own the land, its equity often counts toward your contribution, which can reduce or remove the cash deposit needed.

Do I need a fixed-price building contract?

Most lenders want a fixed-price building contract with a licensed builder, because it sets out exactly what’s being built and for how much. That certainty underpins the on-completion valuation and the staged drawdowns. Cost-plus contracts, where the final price isn’t fixed, are possible but sit with a narrower lender panel and tighter terms.

Can I get a construction loan as an owner-builder?

Yes, but they’re harder to arrange. Owner-builder loans come with lower loan-to-value ratios, a much smaller lender panel and more documentation, because the lender carries more risk without a builder’s contract and warranties. It’s achievable with the right lender and a solid plan.

How does a knockdown rebuild or land-and-construction loan work?

For a land-and-construction purchase, the land settles first, then the build is funded in stages on top. For a knockdown rebuild, the equity in your existing property usually supports the new build, with the loan structured around demolition and then the staged construction.

How is the property valued before it’s built?

The lender orders an “as if complete” valuation based on the land value plus your fixed-price building contract and plans. That figure becomes the basis for your loan-to-value ratio. If the on-completion value comes in below the combined land and build cost, the lender may approve less than expected.

What happens to the loan once the build is finished?

After the final stage is drawn and a completion certificate is issued, the loan typically converts from interest-only on the drawn amount to a standard principal-and-interest home loan on the full balance.

How long does a build take, and what if it runs over?

A standard single-dwelling build often runs around six to 12 months. Construction loans usually allow a set construction period, commonly up to 12 months, with extensions available if the build runs over. We help you build a realistic timeline into the loan and manage any extension with the lender if delays occur.

Ready to Start Building with Loanworx?

Whether you’re a first-time builder or an experienced developer, Loanworx can help you set up construction financing that supports your project from start to finish.

Ready to Start Building with Loanworx?

Whether you’re a first-time builder or an experienced developer, Loanworx can help you set up construction financing that supports your project from start to finish.
Call us on 1300 562 696 or speak with a construction finance specialist today.
Talk to Us

Ready to talk finance?

It’s what we do best. Call us now on 1300 562 696 or fill in the below form to speak to one of our highly skilled brokers.